
- Published
- Oct 30, 2026
- Updated
- Nov 1, 2026
- Reading time
- 11 min read
Google Ads Cart Data: Audit Revenue and Gross Profit
Reconcile Google Ads conversion value, cart revenue and gross profit. Check product IDs, COGS coverage and advertised-versus-sold reports before comparisons.
In this guide (11 sections)
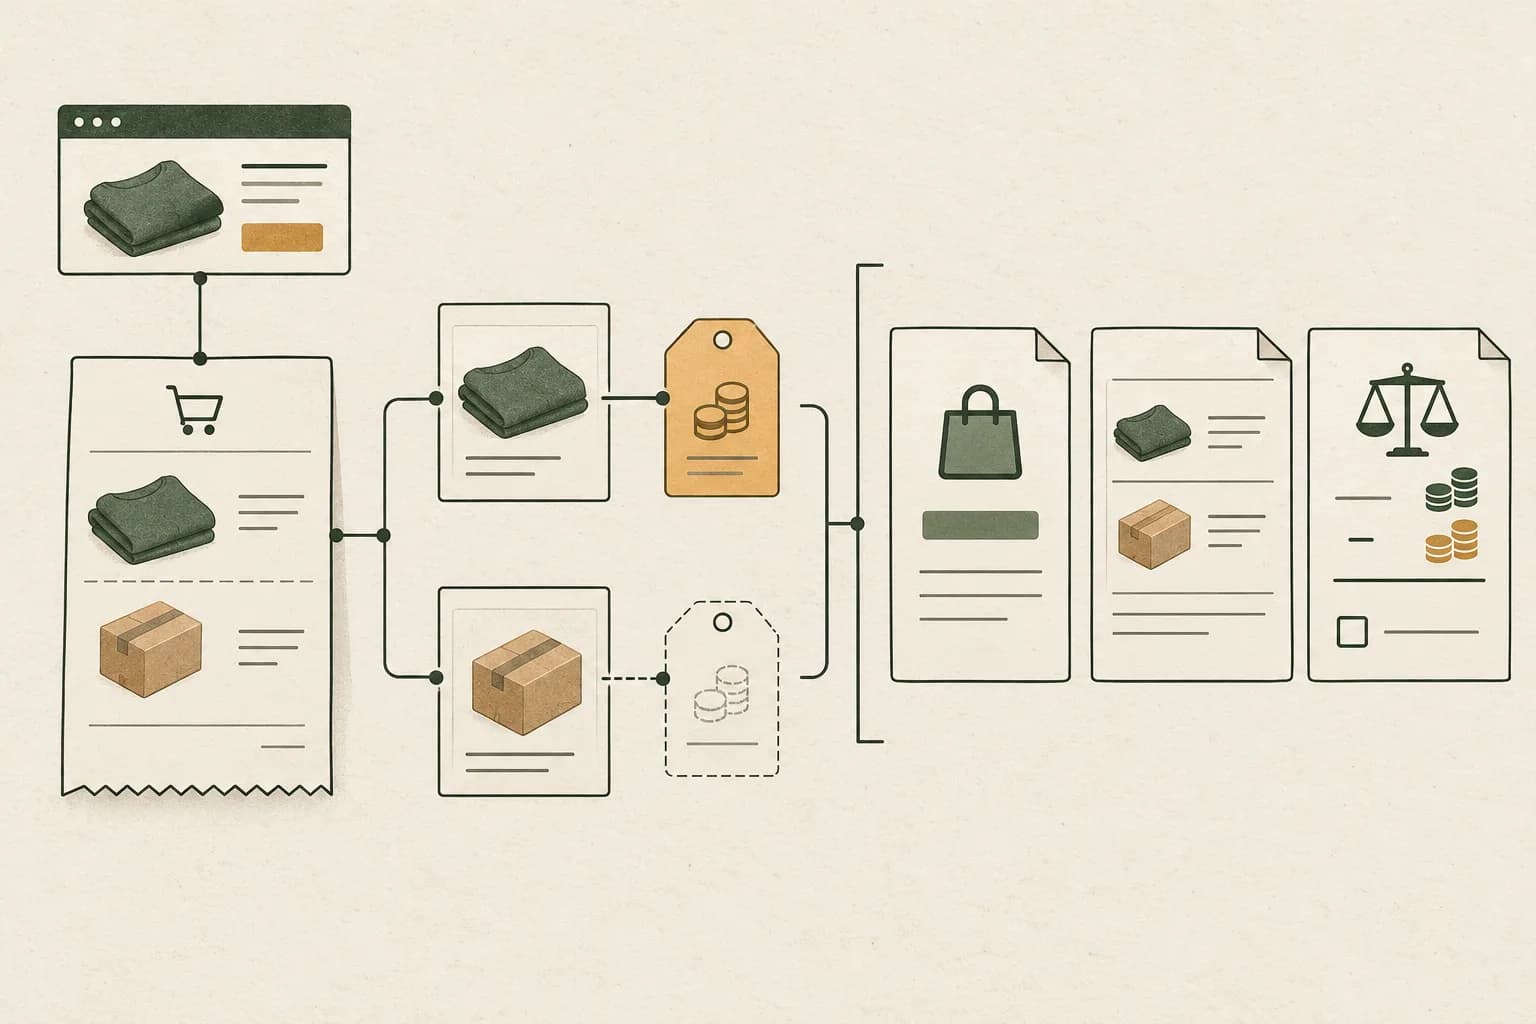
Before comparing product-level profit in Google Ads with your store, establish three things: what the conversion value represents, which sold items match the linked product feed, and whether the report describes the advertised product or the product actually purchased.
A conversion value can represent a configured business signal rather than sales revenue. Cart revenue requires itemized purchase data. Gross-profit reporting additionally depends on cost-of-goods-sold coverage. A populated profit column does not prove every item contributed complete cost data, and attributed sales are not your entire store's sales ledger.
The useful diagnostic is an item-level reconciliation with explicit coverage and report scope. It comes before choosing a reporting connector or changing a bidding target.
Two real questions behind the reporting problem#
An advertiser asks for product-level Google Ads reporting that combines spend, store sales and profit after COGS. Replies propose joining item IDs, while others point out that the product advertised need not be the product purchased. A shared identifier alone cannot resolve that difference in meaning.
Another question about sending margin as conversion value asks whether products with different prices and margins should send a different value signal. The replies mix custom values, native cart reporting and bidding recommendations. This guide separates the measurements; it does not assume that any signal change improves campaign performance.
Both questions need a reporting contract before they need a new tool: the source, event, value definition, product grain, attribution population and cost coverage must be clear.
Define what conversion value represents
A configured conversion value may differ from store revenue and gross profit. Discuss which product and order records can be compared.
Discuss a measurement questionA short inquiry to scope relevant options; no campaign access is needed.
Separate conversion value from cart revenue and profit#
Google's conversion-value reference allows values to express different business objectives. Its reporting reference defines Conv. value as the sum of values for the included conversions. The column's label does not independently validate the financial meaning of those values.
| Measure | Evidence needed | Common interpretation error |
|---|---|---|
| Conv. value | Included actions, configured value policy and transmitted values | Calling every value signal sales revenue |
| Cart revenue | Eligible attributed purchases with sold-item detail | Comparing it directly with all store orders |
| COGS | Matching product costs and their coverage | Treating missing cost as zero |
| Gross profit | Relevant revenue less the corresponding COGS | Calling it net business profit |
If an implementation changes from revenue to a margin-based signal, retain the definition and effective date. A smaller reported value does not itself establish lost sales. Keep the original revenue ledger available and do not relabel a mixed historical series as though its meaning never changed.
The platform measurement comparison guide covers the broader difference between business outcomes and platform credit. This guide adds the product-and-cost joins needed for cart reporting.
Step 1: Verify the purchase population and implementation route#
Google's cart-data overview describes itemized data added to purchase conversion measurement. It also documents supported imported Google Analytics and Firebase routes; do not assume every implementation must use a native Google Ads website tag.
Inventory the actual conversion source, account, action identifier and linked Merchant Center account. Confirm the applicable eligibility and setup requirements for that route. A generic purchase appearing elsewhere in the account does not establish that its cart data is eligible for these reports.
Freeze one comparison period and record timezone, date basis, selected actions, attribution settings, filters and extraction time. Keep the reference order population explicit: accepted orders placed during the period are different from orders credited to earlier ad interactions during a click-date report.
For a GA4 purchase with missing or incorrect revenue before the Ads import is considered, use the GA4 monetary-event diagnostic. Importing an incomplete event does not establish a complete cart.
Step 2: Inspect item parameters using the source-specific contract#
The current cart-data parameter reference distinguishes the item identifier by source: native Google Ads uses items.id, while Google Analytics or Firebase uses items.item_id. Each purchased item needs its price and quantity. Do not copy a payload intended for another source simply because it contains a familiar purchase event.
Create one private test receipt with these checkpoints:
- The accepted business order and its line items.
- The application or data-layer representation.
- The emitted tag or imported-event fields.
- The receiving diagnostic and subsequent report.
For each checkpoint, retain the exact item identifier, unit price, quantity and currency basis. A line containing three units must not become three orders, and a unit price must not silently become the line total before quantity is applied again.
The parameter reference defines item price separately from tax, shipping and transaction-level discounts. It also documents source-specific differences: the order-level discount parameter is not supported for the Google Analytics conversion source. Validate the actual route rather than applying one discount workaround to every implementation.
Record whether discounts have already reduced a source price. Subtracting the same discount twice can produce an apparent revenue shortfall even when the event fires correctly.
Step 3: Prove the Merchant Center join before rolling up products#
The cart-data overview requires sold-item identifiers to match IDs in the linked Merchant Center feed. Preserve the exact feed item ID, associated account/feed context and the store's corresponding product or variant identifier.
Use an explicit lookup rather than a title match or an assumed identifier pattern. Two sizes of one product can have different item IDs, while a business dashboard may group them under a parent product. Document that rollup as a separate transformation after verifying the source IDs.
Give unmatched rows a visible reason: no source item ID, no matching feed item, wrong account context, or an unresolved mapping. Do not quietly discard them from a profit report and leave the remaining rows looking complete.
A useful output is a small join audit with counts at each boundary: purchased line items, eligible mapped items, unmatched items and items carrying usable costs. Define the denominator for every percentage. A high match rate by number of items does not establish the same coverage by sales value.
Step 4: Measure cost coverage before interpreting gross profit#
Google's COGS setup guide identifies the Merchant Center cost_of_goods_sold attribute as the additional input for profit reporting. The Merchant Center specification permits estimates and recommends a consistent currency with the price reported in the conversion.
Keep actual and estimated costs distinguishable in your own evidence. Record the cost source, currency, version or extraction date and missing-value policy. Do not claim an exact accounting profit from a feed populated with approximate costs.
Gross profit here means revenue minus the corresponding COGS. It is not automatically net profit after advertising, fulfilment, overhead or other business expenses.
There is a source-text inconsistency: the metrics reference contains a sentence reversing the subtraction, while its worked examples and the COGS setup guide show revenue minus COGS. Use the corroborated formula; do not reproduce the reversed wording in a worksheet.
Most importantly, inspect what missing costs exclude. A profit figure based on the cost-covered part of a basket cannot safely be presented as the whole basket's profit.
A hypothetical basket with incomplete COGS#
Assume one eligible attributed purchase contains the following items. Prices are merchandise amounts in USD, with no tax, shipping or discounts in this simplified example. These are invented numbers for explanation, not customer results.
| Sold item | Quantity | Unit price | Revenue | Unit COGS available? | Cost-supported gross profit |
|---|---|---|---|---|---|
| Item A | 2 | USD 30 | USD 60 | Yes: USD 18 | USD 24 = 60 − 36 |
| Item B | 1 | USD 40 | USD 40 | No | Unknown |
| Basket | 3 units | — | USD 100 | Incomplete | Whole-basket profit unknown |
There is one order containing three units. Revenue is USD 100. The known cost for Item A is USD 36, and its gross profit is USD 24. Item B's missing cost is not zero.
The cost-covered merchandise represents USD 60 of USD 100 revenue: 60% revenue coverage in this QA worksheet. The cost-supported margin for Item A is 24 ÷ 60 = 40%. Calling that a 40% whole-basket margin would use an unsupported population.
Google's metrics documentation illustrates that items without COGS can be omitted from its gross-profit and margin calculations. Review the actual report population rather than assuming a number proves full coverage.
If a verified unit cost of USD 25 later becomes available for Item B, the completed calculation would be USD 100 − USD 36 − USD 25 = USD 39 gross profit, or 39% of the basket's merchandise revenue. That is a hypothetical completed-cost calculation, not a promise that changing the feed rewrites every historical report identically.
Step 5: Select the advertised or sold-product perspective#
The cart-data metrics guide provides advertised-items, sold-items and cross-sold reports. These views answer different product questions.
If an ad for Item A leads to a basket containing A and B, an advertised-product view can associate the basket with A's advertising interaction. A sold-product view describes the merchandise actually bought. Joining A's advertising spend to B's sold-item row and treating them as interchangeable product performance is not a neutral merge.
Before blending exports, write the row definition at the top of each sheet. Include whether it is an advertised item, sold item or explicit advertised-to-sold relationship, plus the product or variant grain. Preserve those fields through the join.
Cross-sell classifications also need their defined item-ID comparison; grouping variants into a parent product must not silently change the platform's original classification. Keep the original rows and the business rollup side by side.
This explains why a connector can reproduce every source row correctly while the final product report remains misleading. The join needs compatible meaning as well as matching strings.
Step 6: Use diagnostics and repeated checks#
Google's cart-data diagnostics reference identifies mismatched item IDs and missing COGS among the problems to investigate. Its card appears when cart data is being shared, so the absence of the card is not evidence that all purchase tracking is healthy.
Download flagged IDs and compare them with the exact feed rows. Classify the failure before changing tags: collection, mapping, account linkage, missing cost or report selection. Preserve unresolved rows and their owners.
The official implementation test inspects a test purchase's actual request and explicitly warns that one successful order does not prove consistent delivery across all transactions. Sample different basket shapes and relevant source paths, then monitor production diagnostics after an authorized change.
For repeatable QA, retain these acceptance checks:
- Purchase and line-item counts agree with the test receipt's units.
- Source-specific item fields reach the intended conversion route.
- Sold items match the intended feed and product/variant mapping.
- Monetary amounts, discounts and currencies have one documented treatment.
- Cost coverage is reported separately from the resulting profit figure.
- Advertised and sold-product views retain their different row definitions.
What a completed report should disclose#
Label the included conversion actions, reporting dates, attribution basis, currency, item grain and perspective. State which revenue is supported by usable COGS, whether those costs are estimated, and what remains unmatched.
Before comparing an Ads value total with order revenue, separate original purchase value from configured value adjustments. Lifecycle additions and value-rule adjustments need their own reporting bridge; they do not establish additional paid orders or product profit.
Keep conversion-value signal changes separate from improvements in data completeness. Neither a different numerator nor a repaired item join proves advertising caused more orders or increased business profit.
The anonymized fashion-retail delivery-quality case illustrates another boundary: measured ad delivery does not establish orders or sales uplift. For supported delivery comparisons alongside your own Ads and store records, discuss a scoped AdProof review. Bring campaign identifiers, dates, metric definitions and comparable exports; cart parameters, feed costs and platform attribution remain with their owning systems.
Frequently asked questions#
Is Google Ads conversion value always sales revenue?
No. It reflects the values and included actions configured for the report. If the implementation sends a margin-based or other business-value signal, preserve that definition rather than labeling the result revenue.
Why can cart-data orders differ from all store orders?
Cart-data reporting concerns eligible purchase conversions attributed within the selected platform scope. Your store ledger can include other channels, dates and transactions. Match the population before investigating missing events.
Should missing COGS be treated as zero?
No. Missing cost creates incomplete coverage. A profit or margin based only on cost-covered items must not be described as the whole basket's result.
Is matching product IDs enough to join spend and sales?
No. Confirm advertised-versus-sold-product perspective, variant/product grain, attribution and monetary definitions. Correctly matching identifiers cannot repair a comparison between different row meanings.
Define what conversion value represents
A configured conversion value may differ from store revenue and gross profit. Discuss which product and order records can be compared.
Discuss a measurement questionA short inquiry to scope relevant options; no campaign access is needed.